Cash vs Installments: Which Is Better When Buying Property in Hurghada?
Cash vs Installments is one of the most important decisions buyers face when purchasing property in Hurghada. While paying in cash can provide stronger negotiating power and potentially lower the total purchase price, an installment plan can make property ownership more accessible and preserve cash for other needs or investments.
The right choice depends on your available budget, investment goals, cash flow, and the specific payment plan offered by the developer or seller.
Cash Payments When Buying Property in Hurghada
Choosing to pay for a property in cash means paying the agreed purchase price upfront rather than spreading the payments over several years.
For buyers comparing Cash vs Installments, the main attraction of a cash purchase is the possibility of securing a better overall price. Some developers or sellers may offer cash discounts, making the final purchase price lower than the price available through a longer payment plan.
Advantages of Paying in Cash
Potential Cash Discount
Cash buyers may have more room to negotiate, particularly when a developer or seller wants to receive the full amount quickly. The actual discount depends on the project, unit, and current offer.
Lower Overall Cost
A cash purchase can reduce the total cost when the installment option includes additional charges, interest, or a higher installment price.
No Future Installment Commitments
Once the purchase has been completed according to the contract, the buyer does not have to worry about future installments. This can make long-term financial planning easier.
Stronger Negotiating Position
A buyer who can complete the transaction quickly may have more negotiating power than someone relying on a long payment schedule.
Potential Disadvantages of Paying in Cash
The main disadvantage is reduced liquidity. Using a large portion of your savings to purchase a property can leave less money available for emergencies, business opportunities, renovations, furnishing, or other investments.
Before choosing a cash purchase, buyers should make sure that paying upfront does not put unnecessary pressure on their wider financial position.
Installment Payments: How Do They Work?
Installment plans allow buyers to purchase a property by paying a down payment followed by scheduled payments over an agreed period.
The exact structure varies between developers and projects. A payment plan may include a specific down payment followed by monthly, quarterly, or other scheduled installments until the remaining balance is paid.
For buyers considering Cash vs Installments, the biggest advantage of installments is that they reduce the amount of money required upfront.
Advantages of Paying in Installments
Lower Initial Payment
Instead of paying the entire property price immediately, buyers can spread the cost over an agreed period.
Better Cash Flow Management
Keeping more cash available can help buyers manage other expenses or investment opportunities while purchasing the property.
Access to Higher-Value Properties
An installment plan may allow a buyer to consider properties that would be difficult to purchase with their current available cash.
Potential for Capital Appreciation
If the property increases in value while the buyer is completing the payment plan, the buyer may benefit from capital appreciation. However, property prices can also fluctuate, so this should not be treated as guaranteed.
Potential Disadvantages of Installments
Installment plans can result in a higher total purchase cost depending on the developer’s pricing structure and contract terms.
Buyers should carefully check the down payment, installment amount, payment period, administrative fees, maintenance fees, and any additional charges before signing.
It is also important to understand what happens if a buyer wants to settle the remaining balance early or misses a scheduled payment.
Cash vs Installments: Comparing the Total Cost
When comparing Cash vs Installments, buyers should not focus only on the amount they need to pay upfront.
The most important figure is the total amount paid by the end of the purchase.
For example, imagine a property with a cash price of $100,000. If the developer offers a cash discount, the buyer may pay less than the original price.
An installment plan for the same property might require a smaller down payment and spread the remaining balance over several years, but the total contractual price could be higher.
This is why buyers should compare:
- Cash purchase price
- Cash discount
- Required down payment
- Total installment price
- Payment period
- Administrative fees
- Maintenance or service charges
- Early payment conditions
- Late payment penalties
- Handover conditions
The cheapest option is not always the one with the lowest monthly payment. Buyers should calculate the total amount they will actually pay.
Cash vs Installments: Which Saves More Money?
In many cases, paying in cash can save money when a significant cash discount is available and the installment price is higher.
However, this does not automatically mean that cash is always the better financial decision.
For example, a buyer may have enough money to purchase a property in cash but may prefer an installment plan to keep part of their capital available for another investment.
In this situation, the buyer should compare the potential savings from paying cash with the potential benefits of keeping the capital available.
The key question is not simply:
“Which option is cheaper?”
It is:
“Which option gives me the best overall financial outcome?”
What Should You Consider Before Choosing?
1. Your Available Cash
Look at how much money you can comfortably use for the property without exhausting your savings.
A cash purchase should not leave you without sufficient funds for unexpected expenses or other important financial commitments.
2. Your Investment Goals
Consider why you are buying the property.
Are you looking for:
- A holiday home?
- A permanent residence?
- A rental property?
- Long-term capital appreciation?
- A combination of personal use and rental income?
Your investment strategy can influence whether paying cash or using installments makes more sense.
3. The Developer’s Payment Plan
Not all installment plans are the same. Some developers may offer attractive payment schedules, while others may have a significant difference between the cash price and installment price.
Always compare the full contractual cost rather than focusing only on the monthly payment.
4. Potential Cash Discounts
Ask whether the developer offers a discount for full or substantial upfront payment.
Even a relatively small discount can make a difference when purchasing a high-value property.
5. Your Cash Flow
If you choose installments, make sure the scheduled payments are realistic for your income and financial situation.
A payment plan should be manageable throughout the entire contract period, not just at the beginning.
6. Additional Costs
Remember that the property price may not be your only expense. Depending on the project, buyers may also need to budget for maintenance fees, registration costs, furnishing, property management, utilities, and other expenses.
Cash vs Installments: Which Option Is Right for You?
There is no universal answer when comparing Cash vs Installments.
Cash may be better if you:
- Have sufficient available funds.
- Can negotiate a meaningful cash discount.
- Want to minimize the total purchase cost.
- Prefer to avoid long-term payment commitments.
- Want to own the property without future installments.
Installments may be better if you:
- Want to preserve more of your available cash.
- Prefer predictable payments over time.
- Want to maintain liquidity for other investments.
- Do not want to use most of your savings upfront.
- Find a payment plan with favorable terms.
Final Thoughts on Cash vs Installments
Cash vs Installments ultimately comes down to more than the purchase price. Buyers should consider the total cost, payment terms, cash flow, investment objectives, and opportunity cost of using their available capital.
A cash purchase can be attractive when a strong discount is available and the buyer wants to minimize the overall cost. An installment plan can be more suitable when preserving liquidity and spreading payments over time are higher priorities.
Before making a decision, compare the full payment structure and ask the developer or seller for a clear breakdown of the total amount payable.
At Rook Estate, we help buyers compare properties, payment plans, locations, and investment opportunities across Hurghada and the Red Sea coast, making it easier to choose a property strategy that fits your budget and goals.
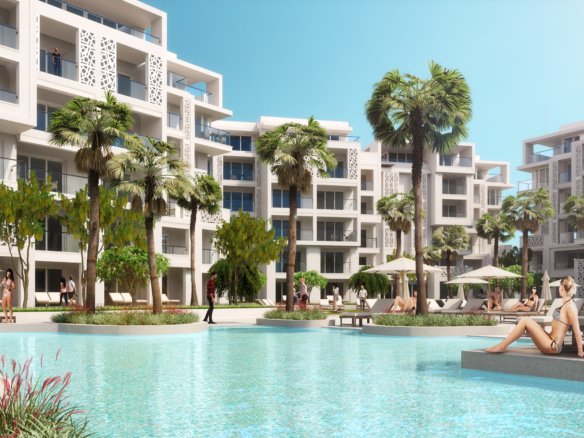
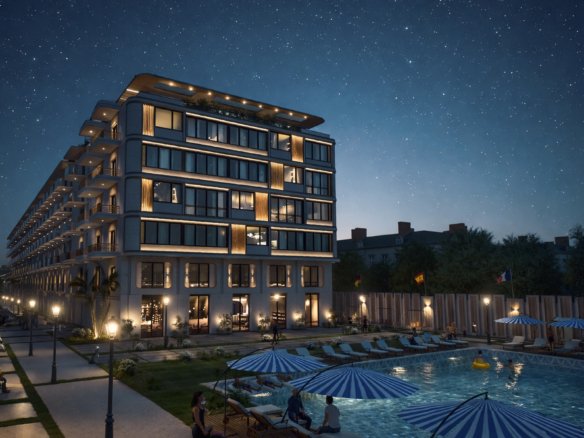
Explore properties for sale in Hurghada or contact Rook Estate to discuss the best payment option for your investment.

Join The Discussion